A home down payment is one of the few savings goals with both a hard number and a hard date. You need a specific, sizeable sum ready by roughly the time you buy, and coming up short simply means you can’t proceed. That combination, a large amount, an essential purpose, and a fixed horizon, calls for saving that is safe, disciplined, and timed to schedule.
A ladder of fixed deposits is built for exactly this. It keeps the money safe, earns more than a savings account, and can be arranged so the whole sum arrives just when you need it.
Why a down payment needs its own savings plan
The down payment is too important to leave to whatever’s left in your account when the time comes. It’s usually the largest cash sum a first-time buyer has to assemble, and the whole purchase hinges on having it ready. Saved loosely, it tends to get spent on other things; saved deliberately, towards a set target, it actually materialises.
It also has an awkward horizon. Five years is too short to ride out the stock market, where a bad year just before you buy could leave you short, but long enough that money idle in a savings account wastes years of return. The goal needs a home that is safe from loss yet still earns something, which points naturally at deposits.
Why choose fixed deposits for a 5-year goal?
For a definite, near-term goal, safety matters more than chasing the highest return. A fixed deposit guarantees both your capital and a known rate of interest, so you can be certain, on the day you need it, that exactly the amount you planned for is there.
That certainty is the whole point for a down payment. An investment that might be worth more, but might also be worth far less in the year you have to buy, is the wrong tool for a sum you cannot do without. Deposits trade the chance of a higher return for the guarantee that the money will be there in full, which is exactly the trade a five-year essential goal calls for.
What a deposit ladder actually is
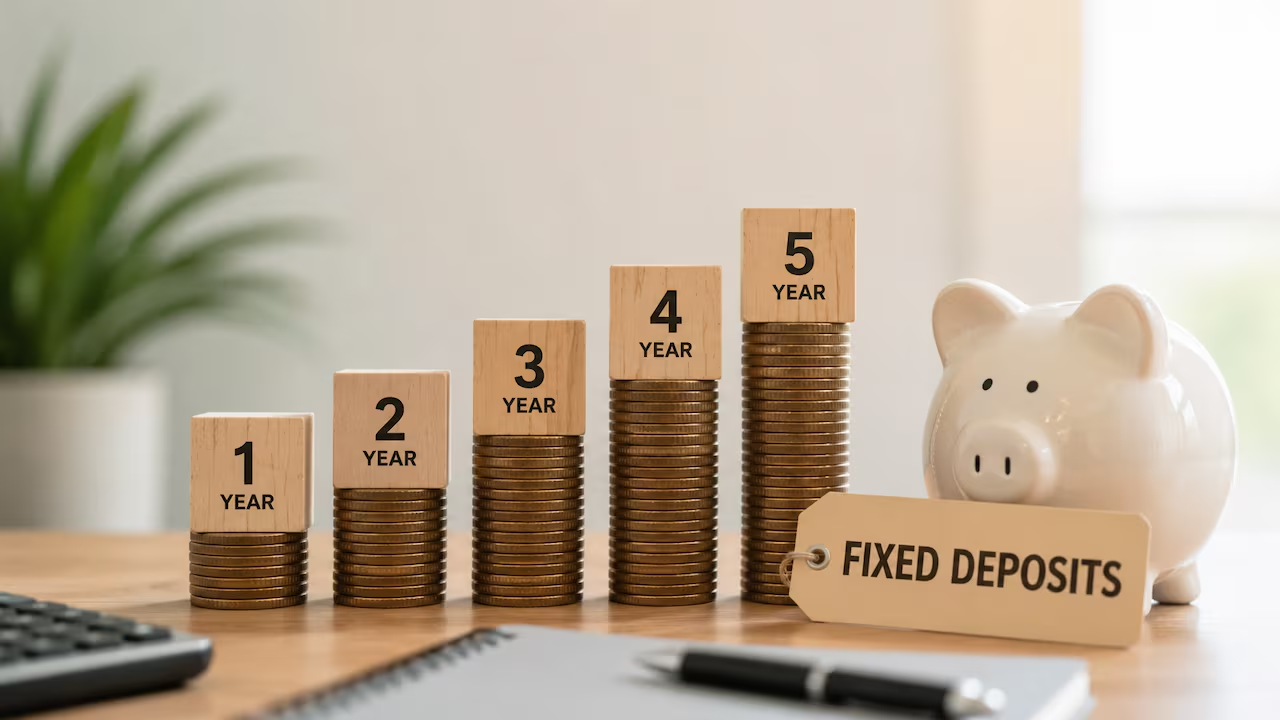
A ladder means spreading your savings across several deposits rather than one, with their maturities staggered and timed around your goal. Instead of a single lump sum locked for five years, you build the pot in tranches, each opened as you save and each set to mature at or near your target date.
Laddering this way through an FD structure does a few useful things at once. Because the deposits are opened at different times, they catch different interest rates, which averages out the effect of rates rising or falling over the five years. It also lets you add to the plan as you go, and staggered maturities keep some flexibility rather than locking everything to a single date.
How do you size and time the tranches?
Start from the finish and work backwards. Fix the amount you need, the down payment plus the associated buying costs, and the date you expect to need it, then divide the saving across the years in between. That tells you roughly how much to set aside each month or quarter, allowing for the interest the deposits will earn along the way.
Timing each tranche is what makes it a ladder rather than a pile. Each deposit should mature at or just before your target date, not long after, so the money is free when you need it rather than locked past the moment you buy. A deposit opened in the second year is given a shorter term than one opened in the first, so both come due around the same window. Done right, the tranches all arrive together, each having earned interest for as long as it was held.
Turning the matured ladder into a down payment
When the deposits mature around your buying date, they combine into the single lump sum the ladder was built to produce. That sum goes straight into your down payment, and every rupee of it reduces what you have to borrow.
That is where the saving pays off twice. A larger down payment means a smaller home loan, which means a lower EMI and less total interest across the tenure, so the saving keeps rewarding you long after the purchase. If you save a little more than the down payment needs, the surplus makes a ready emergency buffer for the first months of owning a home.
How do you keep the plan flexible and on track?
A good ladder leaves you room to breathe. Rather than locking every rupee until the exact buying date, keep a small portion accessible, and remember that if an emergency strikes you can break a single deposit, or borrow against it, without disturbing the rest of the ladder.
Beyond that, the plan mostly runs itself, but it rewards a periodic check. Top the deposits up if property prices lift your target, adjust the maturities if your buying date shifts, and reinvest any that come due early rather than let the cash sit idle. Set the target, ladder the deposits to meet it, and the down payment becomes a dated plan you watch fill up rather than a vague hope you keep deferring.
Email indiaclery@gmail.com with the article link and details.